X12 transaction guide · Healthcare and insurance
EDI 273 Insurance/Annuity Application Status
The X12 document insurers use to tell trading partners the current status of a life insurance or annuity application during underwriting.
- Sent by
- Insurance company
- Received by
- Distributor, such as an agent or broker-dealer
- Standard
- ANSI ASC X12
What is an EDI 273?
The EDI 273 Insurance/Annuity Application Status is the ANSI X12 transaction set insurance providers use to inform their trading partners of the current status of a life insurance or annuity application during underwriting.
Applicants ask their agents how their applications are progressing. Status updates show which requirements are outstanding, whether the application is approved and on what terms, or why it was declined, so agents can keep clients informed and help clear outstanding items. Final updates confirm issue and delivery of the policy, or explain a decline or postponement, so the distributor can close its own case record.
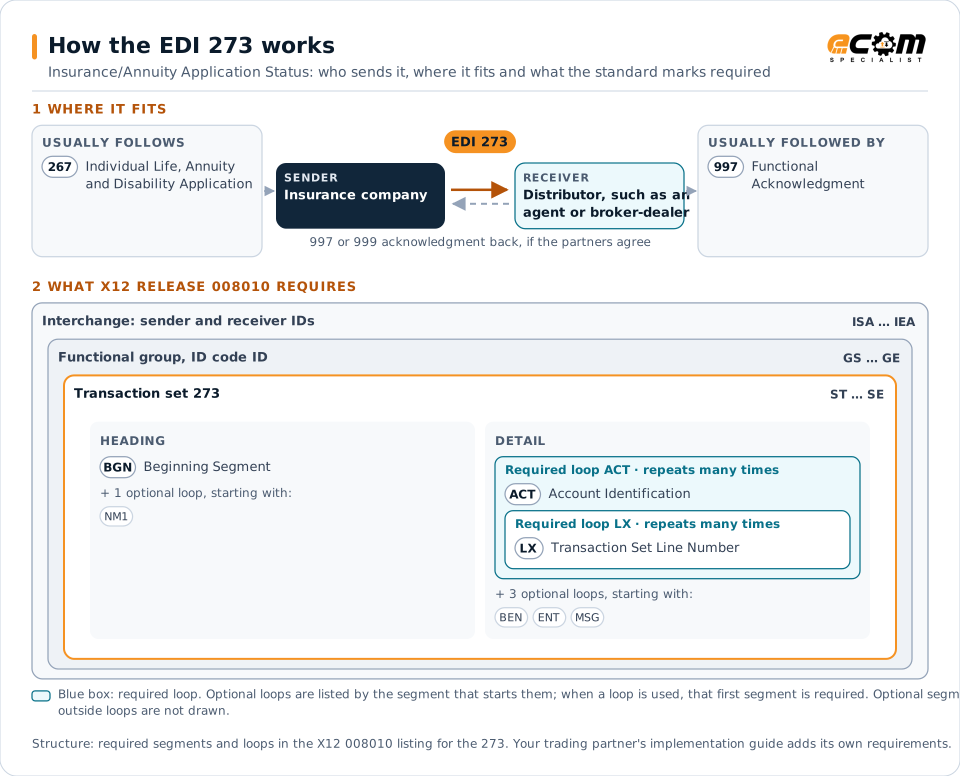
How to read this diagram: the top row shows who sends the 273, to whom, and which documents usually come before and after it. The lower part shows what X12 release 008010 itself requires: the envelopes around the 273 and the segments and loops the standard marks as required, area by area. Optional loops are listed by the segment that starts them rather than drawn in full. This is the standard's minimum, not a trading partner's requirement: each partner's implementation guide usually makes some optional loops mandatory, restricts the codes and may use a different release.
When it is used
- Reporting outstanding underwriting requirements
- Reporting approval, decline or postponement
- Reporting issue and delivery of the policy
Where it fits in the document flow
Structure
Mandatory segments in the 273 (X12 release 008010)
The segments X12 release 008010 marks as mandatory at their level, in order. Segments inside optional loops are needed only when the loop is used. This is the standard's requirement, not your trading partner's: each partner's implementation guide names the release it uses, adds the optional segments it requires and restricts the values. The requirement status comes from one published X12 reference listing and has not been checked against a second source.
- ST
- BGN
- NM1
- ACT
- LX
- BEN
- ENT
- LQ
- BLI
- MSG
- SE
Practical example
The 273 in practice
An agent submitted a life application two weeks ago. The insurer sends a 273 showing the exam and lab results received but a physician statement still outstanding. A week later, another 273 reports approval at standard rates, and the agent arranges policy delivery.
Implementation
Implementation considerations for the 273
- Send updates at each underwriting milestone.
- Describe outstanding requirements clearly.
- Protect applicants' personal data under applicable law.
- Match status messages to the agent's application records.
How ECOM helps
Automate the 273 with ECOM
Industry
Financial Services
Secure file transfer and B2B integration for banks and financial institutions.
Solution
Supply Chain Visibility
Track orders, shipments and invoices across partners and catch exceptions early.
Solution
EDI Integration
Exchange X12 and EDIFACT documents with partners and integrate them directly with your ERP.
More general questions about EDI are answered in the EDI FAQ.
Related transactions
Related healthcare and insurance documents
- 267Individual Life, Annuity and Disability Application
- 100Insurance Plan Description
- 186Insurance Underwriting Requirements Reporting
- 260Application for Mortgage Insurance Benefits
- 263Residential Mortgage Insurance Application Response
- 872Residential Mortgage Insurance Application
- 111Individual Insurance Policy and Client Information
- 252Insurance Producer Administration
- 256Periodic Compensation
- 259Residential Mortgage Insurance Explanation of Benefits
- 268Annuity Activity
- 112Property Damage Report
Need help with the EDI 273?
ECOM maps, tests and monitors X12 documents for your trading partners and integrates them with your ERP.